— The SkyBlue Way
One Conversation. Multiple Condo Insurance Options.
Different insurance companies can look at the same condo owner differently. That’s why having a Sky-Agent® shop available options can make a difference.
We Listen
Tell us about you, your condo and the coverage you’re looking for.
We Shop
Your Sky-Agent® shops available insurance companies for coverage, pricing and discounts that fit your
situation.
You Choose
We explain your options in plain language. You decide what’s right for you.
Ready to See What a Sky-Agent® Can Find for You?
Your condo association has insurance. That doesn’t mean you have all the insurance you need.
CONDO INSURANCE 101
Your Condo Association Has Insurance. So Why Do You Need Your Own?
Your condominium association generally carries insurance for property owned or maintained by the association, such as common areas and certain portions of the building. But the association’s policy isn’t a replacement for your own Condo Insurance.
Your individual policy can provide protection for your personal belongings, personal liability, Loss of Use and certain parts of your unit you’re responsible for, depending on the policy and circumstances.
The association protects its interests. Your Condo Insurance helps protect yours.
YOUR CONDO UNIT
What Part of Your Condo Are You Responsible For?
Condo ownership is different from owning a traditional single-family home. The condominium association is generally responsible for certain parts of the property, while you are responsible for your individual unit and belongings.
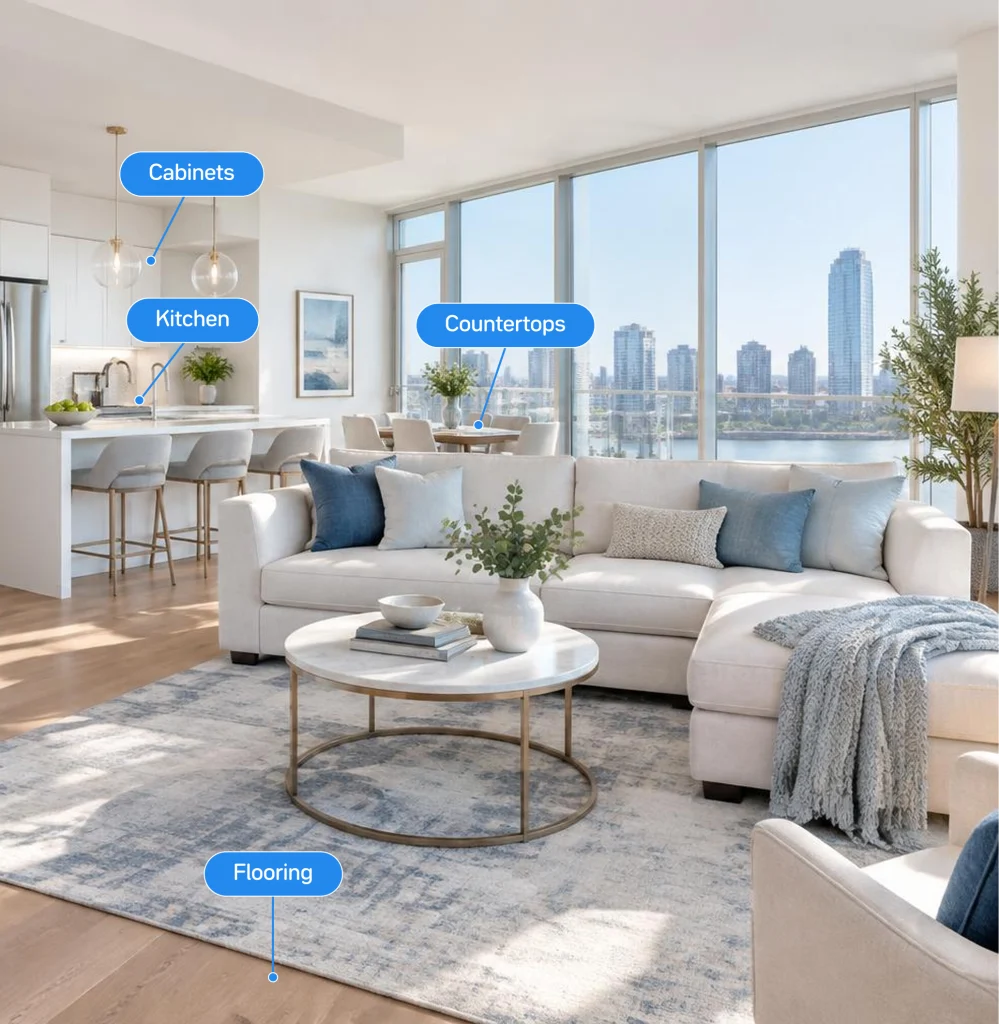
Your Condo Insurance may help protect covered property within your unit, including certain:
- Interior fixtures
- Cabinets and countertops
- Flooring
- Built-in appliances
- Interior improvements and upgrades
Exactly what’s covered depends on the policy, the loss and your individual circumstances.
You may share the building. You still need protection that’s yours.
IMPROVEMENTS & UPGRADES
Made Your Condo Your Own? Protect the Investment.
Condo owners often put significant money into improving their units: new flooring, upgraded cabinets, custom countertops, built-ins, renovated bathrooms and updated kitchens. Those improvements can increase what you have invested inside your condo. Your Sky-Agent® can help you consider the coverage available for eligible improvements and additions so your policy better reflects the home you’ve created.
The association may own or maintain parts of the building. You invested in what’s inside your unit.
PERSONAL PROPERTY
Your Condo Is More Than Walls and Fixtures.
Furniture, clothing, electronics, computers, appliances, décor and the other things you’ve accumulated can represent a substantial investment. Personal Property coverage can help protect your belongings against covered losses, subject to your policy’s terms, limits and deductible.
Protect more than the expensive things. Protect the everyday things that make your condo home.
An Important Coverage Difference
Replacement Cost vs. Actual Cash Value
The amount of personal-property coverage you select matters. How your belongings are valued after a covered loss matters too.
Replacement Cost
Actual Cash Value
What you originally paid for something, what it’s worth today and what it would cost to replace it can be very different numbers.
Don’t compare Condo Insurance on price alone. Know what you’re buying.
CONDO-SPECIFIC PROTECTION
What Is Loss Assessment Coverage?
Sometimes a condominium association may assess individual unit owners for their share of certain losses or expenses involving commonly owned property.
Depending on the circumstances and policy, Loss Assessment coverage can help with certain eligible assessments resulting from a covered loss, subject to the coverage limit, terms and exclusions.
Not every association assessment is covered.
That’s why understanding what your Condo Insurance actually provides matters.
PRICE & VALUE
How Much Does Condo Insurance Cost?
There isn’t one standard price for Condo Insurance. Insurance companies can consider factors such as:
- Location
- Characteristics of the condo
- Coverage limits
- Deductibles
- Personal Property coverage
- Claims history
- Safety and protective features
- Available discounts
Different insurance companies can evaluate the same condo differently.
That’s Why We Shop.
Your Sky-Agent® can compare available insurance companies and help you look for the combination of
coverage and price that fits your situation.
SAVE MORE
Condo Insurance Discounts
Available discounts vary by insurance company, but there may be several opportunities to save.
Multi-Policy
Protective Devices
Claims History
Payment Options
Your Sky-Agent® knows what to ask—and where to look.
Shop the Total Cost
Condo + Auto May Be Better Together.
If you insure a vehicle in addition to your condo, shopping the policies together can sometimes change the economics of both.
Some insurance companies offer valuable multi-policy discounts when eligible Auto and Condo Insurance are combined.
So don’t look only at your Condo Insurance premium. Ask what it costs to protect your condo and vehicles together.
Your Sky-Agent® can shop available combinations and help you compare the total insurance picture, not simply one policy at a time.
Don’t Just Bundle. Shop the Bundle.™
Shop the Whole Picture
Your Condo May Be Home. It Isn’t the Only Thing You Protect.
You may also have:
A Sky-Agent® can look beyond your Condo policy and help you explore available options across your household.
One conversation can open the door to multiple insurance options.
WHY SKYBLUE
A Better Way to Shop for Condo Insurance.
Multiple Insurance Companies
Licensed Nationwide
Real Human Help
More Than Condo Insurance
Easy to Get Started
One Conversation. Multiple Insurance Options.
THE SKY-AGENT® DIFFERENCE
Condo Insurance Doesn’t Have to Be Complicated.
Condo ownership comes with some insurance considerations you don’t necessarily encounter when renting or owning a traditional house.
What should you insure inside your unit? How much Personal Property coverage do you need? What is Loss Assessment? Replacement Cost or Actual Cash Value? Should you shop Condo and Auto together? That’s exactly why having an agent matters.
A Sky-Agent® can shop available insurance companies, explain the differences and help you understand your options.
We shop. We explain. You choose.
Nobody Shops Alone.™
Frequently Asked Questions
Condo Insurance FAQs
Still have questions? Ask a Sky-Agent®.
Both can provide important property and liability protection, but they’re designed for different types of homeownership. Traditional Homeowners Insurance generally insures the house itself along with other covered property and exposures. With a condominium, the association generally insures certain portions of the building and common property, while your individual Condo Insurance policy helps protect your unit, belongings, personal liability and other eligible exposures. If you own a condominium unit, tell your Sky-Agent® what you own and we’ll help you shop the appropriate type of coverage
An HO-6 is a type of insurance policy commonly used for condominium unit owners. Depending on the policy, it can provide coverage for certain parts of your unit, Personal Property, Personal Liability, Loss of Use and other eligible exposures. You don’t need to know the policy form before calling us. Tell your Sky-Agent® you own a condo. We’ll take it from there.
Your condominium association generally carries insurance for property owned or maintained by the association, such as common areas and certain portions of the building. But the association’s insurance isn’t a replacement for your own Condo Insurance. Your individual policy can provide protection for your belongings, personal liability, Loss of Use and certain parts of your unit you’re responsible for, depending on the policy and circumstances.
Coverage may be available for eligible improvements and upgrades you’re responsible for inside your condo, subject to the policy’s terms and limits. If you’ve renovated the kitchen, installed new flooring, upgraded cabinets or made other significant improvements, tell your Sky-Agent® so those features can be considered when shopping your coverage.
Sometimes a condominium association may assess individual unit owners for their share of certain covered losses or expenses involving commonly owned property. Loss Assessment coverage can help with certain eligible assessments resulting from a covered loss, subject to the policy’s terms, limits and exclusions. Not every HOA assessment or special assessment is covered. Your Sky-Agent® can help explain the coverage available to you.
It can, depending on what caused the damage. Condo Insurance may cover certain sudden and accidental water losses when the cause is covered by the policy. Coverage can vary substantially depending on the source of the water and circumstances of the loss. Flooding from rising surface water, for example, generally requires separate Flood Insurance rather than standard Condo Insurance. If water protection is important to you, ask your Sky-Agent® about available coverage and exclusions.
Personal Property coverage can help protect furniture, clothing, electronics and other belongings against covered losses, subject to policy terms, limits and deductibles. Certain categories of valuable property may have special limits, so tell your Sky-Agent® about jewelry, collectibles or other higher-value belongings.
There isn’t one answer that fits every condo owner. Consider the value of your belongings, improvements you’ve made inside the unit, the liability protection you want and the other coverage available under the policy. Your Sky-Agent® can explain available limits and options so you can make an informed decision.
Yes. Many insurance companies offer multi-policy discounts when eligible Condo and Auto policies are written together. But the biggest bundle discount doesn’t automatically mean the lowest total insurance cost or best overall protection. Don’t Just Bundle. Shop the Bundle.™ Your Sky-Agent® can compare available options and help you look at the total insurance picture.
Tell your Sky-Agent® that the condo is tenant-occupied. A condo you live in yourself and a condo you own as a rental property can have different insurance needs and underwriting requirements. We’ll help you shop coverage appropriate for how the property is actually used.
SkyBlue is licensed nationwide. Available insurance companies and products vary by state and individual property, but a Sky-Agent® can help shop the Condo Insurance options available to you.
CONDO INSURANCE RESOURCES
Understand Your Condo. Understand Your Coverage
Sea-Doo Insurance: What Personal Watercraft Owners Should Know
Jet Ski and personal watercraft insurance can help protect you from accidents, theft, damage, liability, and other risks on the water. Learn what PWC insurance…
Read the guideReplacement Cost vs. Actual Cash Value for Condo Insurance: What’s the Difference?
Jet Ski and personal watercraft insurance can help protect you from accidents, theft, damage, liability, and other risks on the water. Learn what PWC insurance…
Read the guideJet Ski Insurance 101: What Every Personal Watercraft Owner Should Know
Jet Ski and personal watercraft insurance can help protect you from accidents, theft, damage, liability, and other risks on the water. Learn what PWC insurance…
Read the guideNOBODY SHOPS ALONE.™